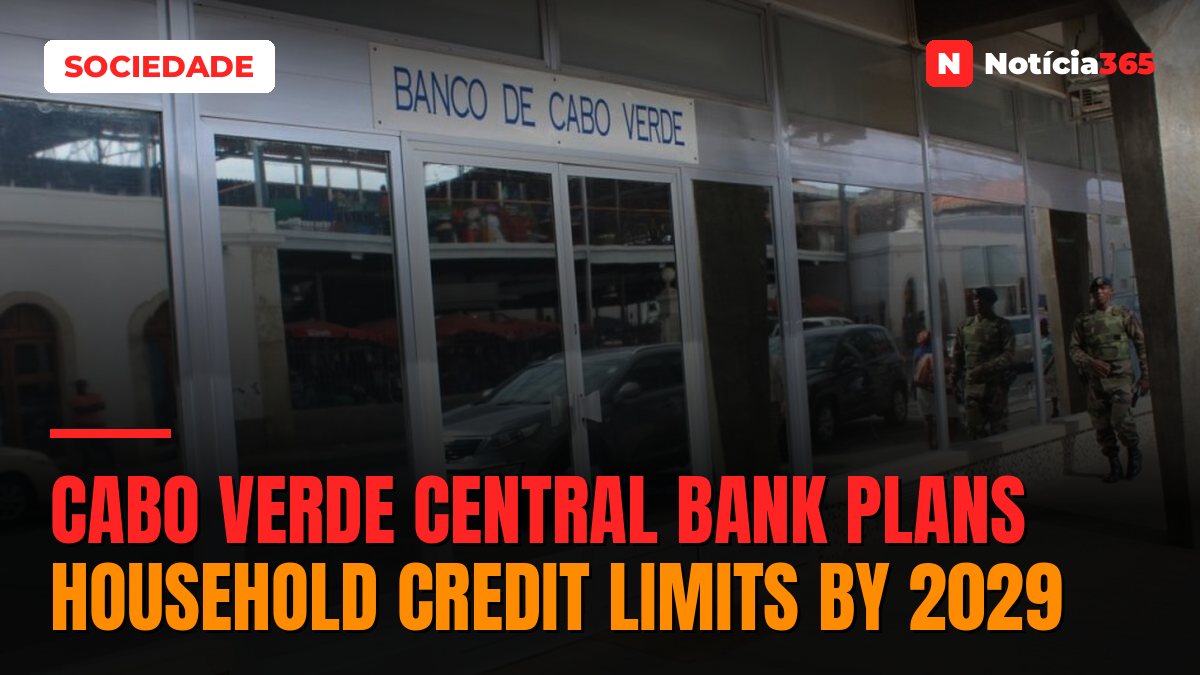

The Bank of Cabo Verde (BCV) is preparing to introduce limits on the share of loan repayments relative to household income, as well as caps on loan amounts relative to the value of collateral property. The measures are expected to enter into force by the end of 2029.
In a statement, the institution said its Board of Directors approved, on 30 October, a roadmap for the implementation of borrower-based macroprudential instruments.
The initiative responds to a commitment made by the central bank under the programme supported by the International Monetary Fund’s Extended Credit Facility (ECF).

The measures will apply to new credit contracts extended to households and focus on two indicators. The first establishes a limit on the loan-to-value (LTV) ratio — that is, the ratio between the loan amount and the value of the property offered as collateral. According to the BCV, this mechanism is intended to reduce losses by financial institutions in the event of borrower default.
The second instrument provides for a cap on the debt-service-to-income (DSTI) ratio, controlling the weight of loan repayment obligations relative to the borrower’s financial capacity.
The timeline presented by the BCV is indicative in nature and foresees that the limits will be approved and enter into force by the end of 2029.
The process will include an adaptation period for financial institutions, as well as mechanisms to monitor and assess the effects of the measures.
Through these instruments, the central bank aims to strengthen risk management associated with household lending and contribute to the stability of the financial system.
Source: Diário Económico
Original article: https://www.diarioeconomico.co.mz/2026/11/06/mundo/africa/cabo-verde-bcv-prepara-limites-ao-credito-das-familias-e-preve-aplicacao-ate-2029/