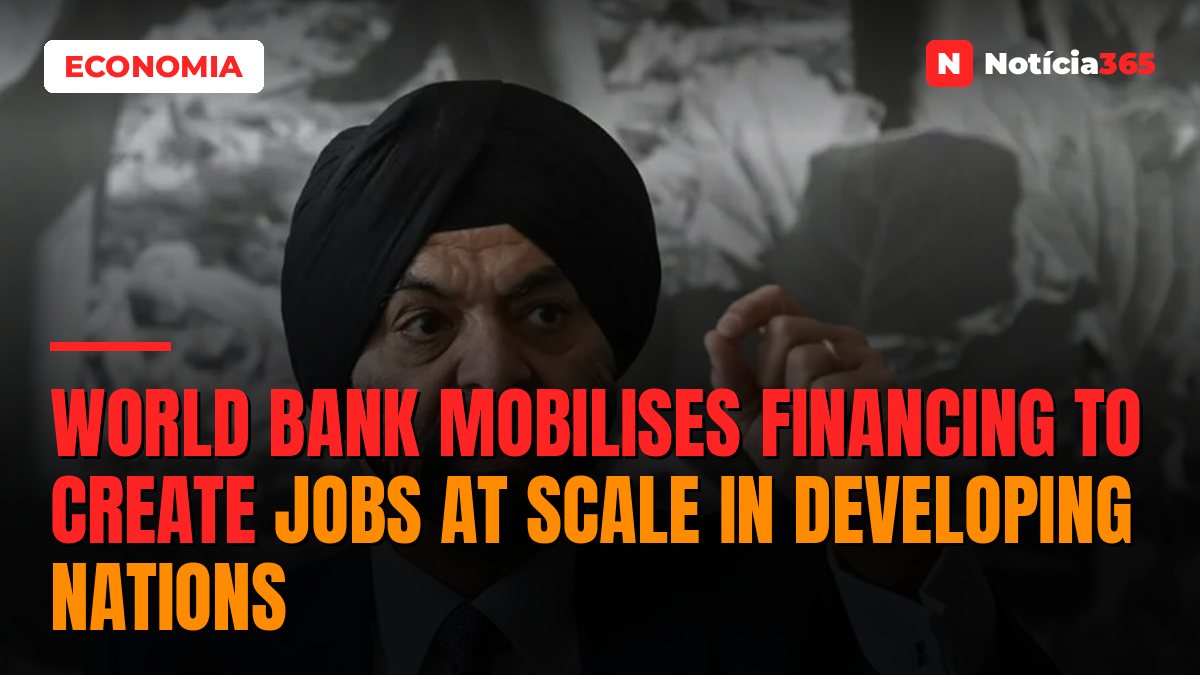

The World Bank is stepping up the mobilisation of public and private financing and promoting institutional reforms to help developing countries create jobs at scale. The strategy was presented by the institution's president, Ajay Banga, during the plenary session of the 2026 Annual Meetings, held on 16 October in Bangkok, Thailand. The initiative comes against a backdrop of rising debt, conflict, and elevated costs for essential goods such as energy and fertilisers.
According to Ajay Banga, the challenge is compounded by a growing youth population and a shortage of employment opportunities. Over the next ten to fifteen years, approximately 1.2 billion young people will enter the labour market, which is expected to offer only 400 million jobs. "Both must be addressed together," he said, arguing that available resources must be deployed more effectively while simultaneously supporting countries in generating large-scale employment.
To address these challenges, the World Bank is restructuring its internal processes and expanding its financing capacity. The time required to prepare projects has been cut from 19 months to nine, while the number of assessment indicators has been reduced from 153 to 22, with a sharper focus on outcomes. The institution has also raised the share of results-based financing from roughly one third to one half, and has created more than US$100 billion in additional lending capacity through the International Bank for Reconstruction and Development (IBRD) over a decade.

Beyond internal reforms, the institution is deepening cooperation with other multilateral development banks to mobilise greater resources and avoid duplication of effort. According to Ajay Banga, the co-financing portfolio has tripled in two years, now spanning around 250 projects that seek to mobilise US$138 billion. This cooperation aims to improve coordination among institutions and enhance the impact of investments in recipient countries.
The job-creation strategy rests on three pillars, beginning with investment in infrastructure and human development. Companies require electricity, water, transport, and internet access, while workers need healthcare, education, and vocational training. Over the past year, the World Bank Group committed US$40 billion to these areas — equivalent to nearly one third of its total financing.
The second pillar consists of making public policies and the rules governing businesses more predictable. According to Ajay Banga, strong institutions, good governance, and streamlined administrative procedures are essential to incentivise investment and facilitate business growth. Over the past year, approximately 30% of the institution's public-sector financing was directed towards institutional and policy reforms, including measures to improve the business environment.
"Success comes when we are no longer needed"
The third pillar aims to increase private investment by reducing the risks that deter companies from advancing new projects. In this context, the Private Sector Investment Lab has been helping to identify obstacles such as currency fluctuations and difficulties in accessing financing. By lowering these barriers, the World Bank intends to create conditions for more companies to invest, expand their operations, and generate employment.
Ajay Banga also argued that financing must be tailored to the needs and development level of each country. In economies with greater needs and risks, concessional public financing — that is, financing extended on terms more favourable than those available on the market — will remain essential. As countries grow stronger, private investment and market access should assume an increasingly prominent role. He highlighted that 35 countries have graduated from the International Development Association (IDA) to the IBRD, while 23 countries have become donors to IDA itself.
For Ajay Banga, the success of this strategy depends on the ability to combine public financing, private investment, philanthropy, and technology according to each country's needs. The objective is to strengthen economies, broaden employment opportunities, and gradually reduce dependence on external support. "Success comes when we are no longer needed," said the World Bank Group president, advocating a development model that enables countries to finance their own growth.
Source: Diário Económico
Original article: https://www.diarioeconomico.co.mz/2026/10/29/mundo/banco-mundial-mobiliza-financiamento-para-criar-empregos-em-grande-escala-nos-paises-em-desenvolvimento/